


IOL Fluorochemical Weekly Report: Refrigerant Market Strongly Performing Amid Peak Season Demand and Quota Constraints
ChinaIOL
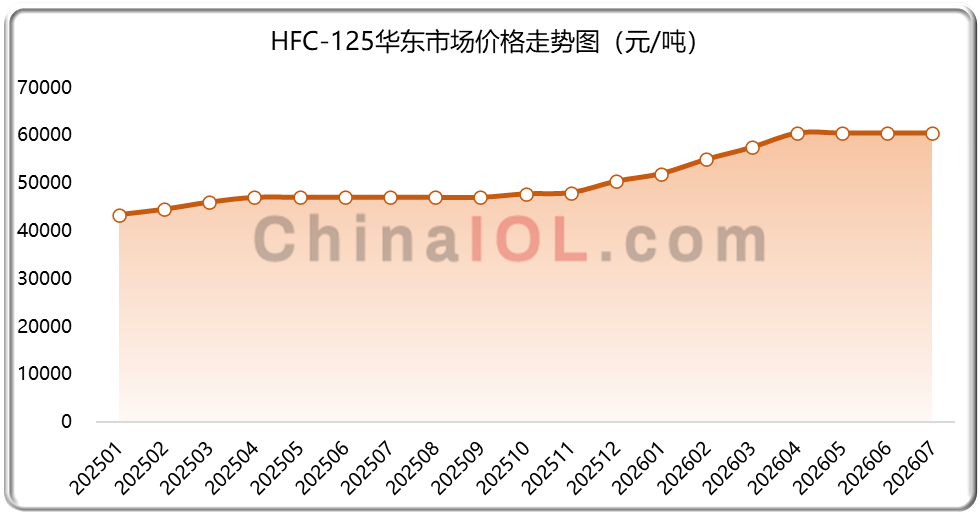
Refrigerant: Strong market performance driven by peak season demand and quota constraints
This week, the refrigerant market remained robust, with prices holding firm. Weekly market highlights: Supply side: Annual production was constrained by rigid quotas, leading major companies to proactively control output to maintain prices. Overall supply remained tight, with a strong upward mindset. Cost side: Upstream raw materials were affected by weak production and sales, resulting in more declines than gains in prices. The inspection and rectification at Inner Mongolia's Jinhubo factory led to a temporary shutdown, directly tightening the supply of fluorite powder and hydrofluoric acid. Demand side: Domestic high-temperature seasonality, strong cold chain demand, and incremental growth in the new energy sector created three driving forces, sustaining the market's robust performance. However, it should be noted that recent escalations in the U.S.-Iran conflict have made it difficult for export orders to improve significantly in the short term, likely remaining dominated by small orders driven by essential needs. Overall, the tight supply-demand balance in the industry is unlikely to change in the short term, and the market will continue to operate at high levels.
ChinaIOL
Fluorinated polymers: Traditional products consolidate under pressure, while high-end products resist declines and see some price increases
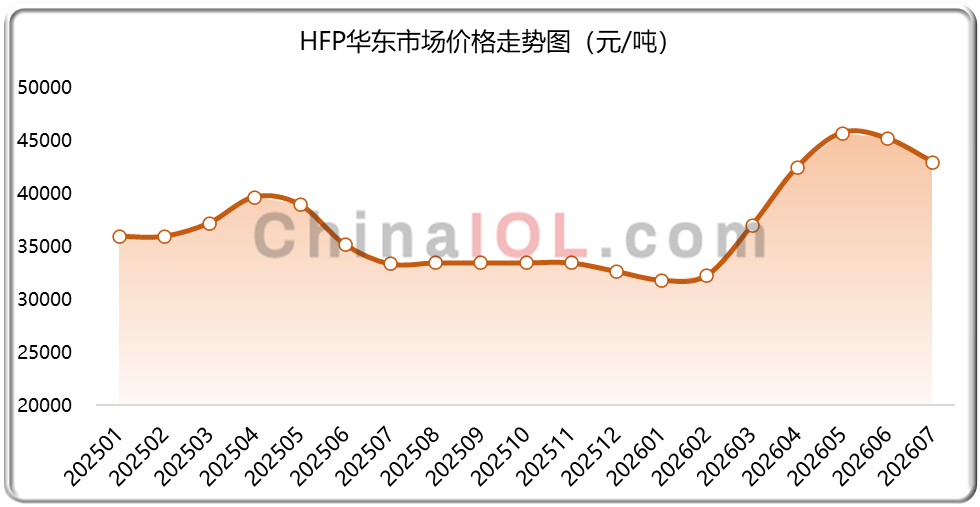
This week, the fluoropolymer market faced rising supply-demand pressure, with declining cost support, leading to price fluctuations for mainstream products. On the cost side, upstream core raw materials such as hydrofluoric acid and chloroform showed mixed price movements, maintaining overall stable cost support. On the supply side, manufacturers steadily accumulated inventory, resulting in weak overall shipments and persistently declining market bargaining power. On the demand side, traditional downstream sectors experienced relatively weak demand, with only minor activity in certain general-purpose applications. During market volatility, end-users predominantly adopted demand-driven purchasing strategies, cautiously observing the market, with minimal bulk stockpiling. The high-end specialty segments demonstrated structural growth, as advanced semiconductor processes and AI computing power industries continued to drive demand expansion for high-value fluoropolymer materials. Premium products such as electronic-grade hydrofluoric acid, high-purity fluorinated specialty gases, semiconductor-grade PFA and PTFE, and AI data center liquid cooling fluorinated fluids exhibited significantly better supply-demand dynamics compared to standard-grade products. Overall, traditional product categories saw loosening cost benchmarks and increasing supply-demand pressure, while high-end fluoropolymer materials experienced differentiated trends driven by AI and semiconductor demand growth, showing relatively stronger resistance to price declines or even price increases.
Weekly Highlights
01Yonghe Shares anticipates a 70%-103% increase in net profit for the first half of 2026
On July 2, Yonghe Co., Ltd. (605020.SH) released its preliminary performance forecast for the first half of 2026. The announcement revealed that the company is expected to achieve a net profit attributable to shareholders of listed companies of 460 million to 550 million yuan in the first half of 2026, representing a year-on-year increase of 69.51% to 102.68%. On a quarterly basis, the company's net profit in the first quarter of 2026 was 180 million yuan, with the second quarter projected to reach 280 million to 370 million yuan, marking a month-on-month growth of 55% to 105%. Both the scale and growth rate of quarterly profits showed an upward trend. Regarding the significant performance growth, the announcement identified two core driving factors: the fluorocarbon chemical business maintained high operational momentum; and the fluorine-containing polymer materials business continued to enhance its profit contribution.
02Jinshizhizai Holding's subsidiary Jin'ebao Fluorine Chemical temporarily suspends production
On July 8, Jinshi Resources issued an announcement regarding significant matters related to its controlling subsidiary. The announcement revealed that, in accordance with safety production requirements, the company's controlled subsidiary, Inner Mongolia Jin'ebor Fluorine Chemical Co., Ltd. (hereinafter referred to as "Jin'ebor Fluorine Chemical," with the company holding a 51% stake), is conducting hazard inspections and rectification efforts, and has implemented temporary production suspension measures. According to the production plan, the subsidiary produces approximately 20,000 tons of anhydrous hydrogen fluoride monthly, and the temporary shutdown is expected to impact short-term operations.
03Zibo Fluorine New Resources Announces the 1,000-Ton PTFE Production Project
On July 7, the Huantai Branch of the Zibo Municipal Ecological Environment Bureau announced the acceptance of the environmental impact assessment documents for the annual production of 1,000 tons of polytetrafluoroethylene resin by Zibo Fluorine New Resource Comprehensive Utilization Co., Ltd. The project is located in the Zhongnan Gaokang Scientific and Intelligent Future Industrial Town, south of Sanying Road and west of Yaochang Road in Guoli Town, Huantai County. With an estimated investment of 5.6 million yuan, the project will produce 500 tons of polytetrafluoroethylene dispersion resin and 500 tons of polytetrafluoroethylene suspension resin annually upon completion.
04Tianci Materials: Net Profit in the First Half of 2026 Expected to Surpass 10-Fold Growth
On the evening of July 9, Tinci Materials disclosed its 2026 semi-annual performance forecast, projecting a net profit attributable to the parent company of 2.7 to 3.0 billion yuan for the first half of the year, representing a year-on-year growth of 907.84% to 1,019.82%. The company also anticipates a non-GAAP net profit attributable to the parent company of 2.65 to 2.95 billion yuan, with a year-on-year increase of 1,029.57% to 1,157.44%. According to the forecast, the primary drivers of the performance growth include strong market demand for lithium-ion battery materials such as electrolytes and lithium hexafluorophosphate, leading to significant sales growth and steady improvements in production capacity utilization. Additionally, ongoing optimization of the industry's supply-demand balance has contributed to rising product market prices, collectively driving an overall increase in gross margins.