


IOL Fluorochemical Weekly Report: Refrigerant Supply Side Reduces Production, Short-Term Strong Performance Continues
ChinaIOL
Refrigerant: Supply-side production cuts lead to market consolidation
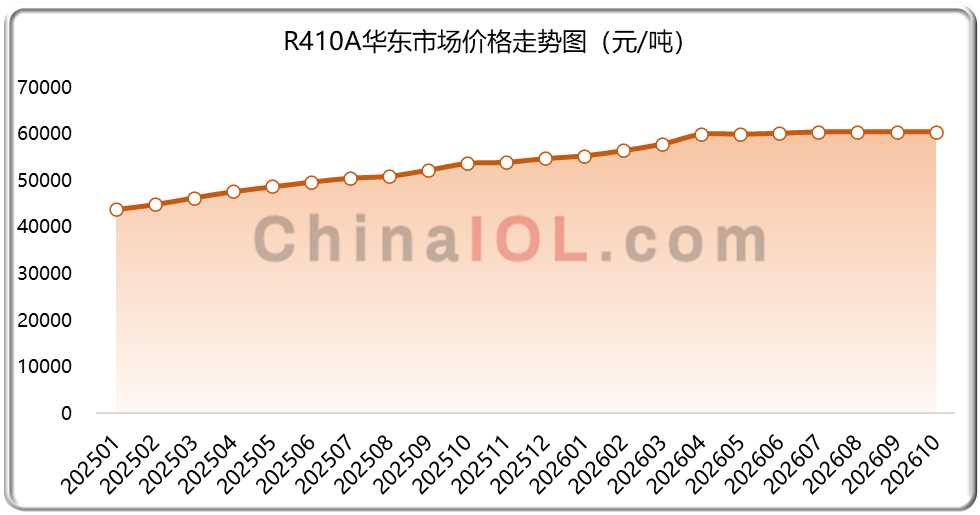
This week, the refrigerant market remained largely stable with no significant price adjustments. Key market dynamics: **Supply side**: Leading companies continued their "quantity control to maintain prices" strategy, with generally low utilization rates during the off-season. Expectations suggest an increase in maintenance and shutdowns in the coming period. **Cost side**: Fluorspar powder supplies were tight, driving price increases; hydrogen fluoride prices declined slightly by 300-400 yuan/ton monthly due to weak demand. Other raw material products showed mixed performance in production and sales, with prices fluctuating. **Demand side**: Holiday effects compounded seasonal weakness, resulting in subdued market activity. Downstream buyers primarily focused on replenishing essential stock, with limited willingness for large-scale inventory accumulation. Traders prioritized clearing existing stockpiles. Meanwhile, the slowdown in HFC phase-down processes in the U.S. and U.K., along with year-end quota baseline effects in the Middle East and India, still provided some support for export demand. Overall, the market will maintain a structural divergence characterized by "supply-side constraints and weak demand-side performance." Pricing authority remains largely on the
supply side, with expectations of continued strong market performance in the short term and minor price fluctuations for certain products.
ChinaIOL
Fluorine-containing polymers: Multiple bearish factors converge, prices under pressure, weak stability, and wait-and-see stance
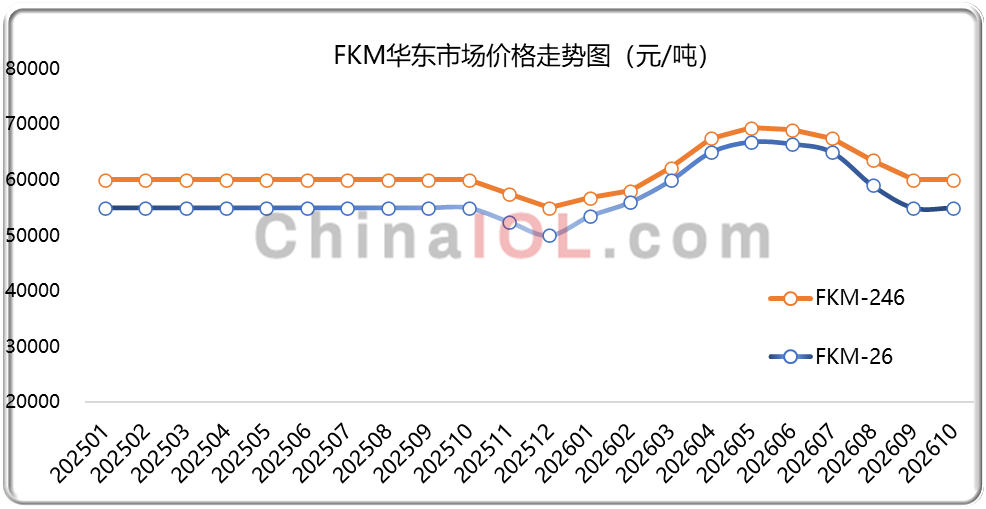
This week, the fluoropolymer market saw stable cost support and high supply-demand pressure, with prices remaining weakly stable under pressure. On the cost side, fluorite's high prices and declining sulfuric acid pushed hydrofluoric acid prices down slightly; methanol surged over 20% in a single month due to geopolitical factors and reduced imports, driving chloroform prices to stabilize and rise moderately, providing strong cost support for the TFE series. Intermediate products like R22, R152a, and R142b faced persistent price pressure from both upstream and downstream impacts. On the supply side, growing supply volumes combined with weak shipments forced companies to reduce production loads and actively manage inventory pressure. On the demand side, traditional applications were in a seasonal downturn, with both volume and prices weakening, as end-users purchased based on demand. The lithium battery and automotive supply chains leveraged strong bargaining power to push prices downward, intensifying competition among resource providers, material manufacturers, and battery companies. Notably, structural growth was concentrated in high-end segments: advanced semiconductor processes, AI computing infrastructure, and new energy sectors continued driving demand for high-value-added products. Short-term production and sales of electronic-grade hydrofluoric acid, high-purity fluorinated specialty gases, semiconductor-grade PFA and PTFE, and AI data center liquid cooling fluorinated fluids remained relatively low, with the price gap between high-end electronic-grade PTFE and general-grade nearing threefold. Overall, new demand in popular applications was still in the early stages of growth with limited scale, while the oversupply of low-end general-purpose materials persisted. As a result, the overall supply-demand imbalance in fluoropolymers remained prominent, with prices continuing to face weak pressure and maintain stability.
Weekly news
01Ministry of Ecology and Environment: 19 companies plan to adjust their HFC quotas for 2026
According to the relevant provisions of the Air Pollution Prevention and Control Law of the People's Republic of China, the Regulations on the Management of Ozone Depleting Substances, and the Notice on Issuing the Total Quota Setting and Distribution Plan for Ozone Depleting Substances and Hydrofluorocarbons in 2026, the Ministry of Ecology and Environment has accepted the application for adjusting the production quota of Hydrofluorocarbons in 2026 submitted by 19 enterprises including Inner Mongolia Yonghe Fluorochemical Co., Ltd. From the proposed adjustment of quotas, it can be seen that the production quotas for R32, R125, and R245fa have decreased, while the production quotas for R134a, R143a, R227ea, and R152a have increased. The total quantity of HFCs has changed as follows: the production quota has decreased by 1141 tons, and the domestic production quota has increased by 504 tons.
02Weihua New Materials: The 10000 ton/year HFO1234yf project is currently undergoing trial production
On September 29th, Weihua New Materials released an investor relations activity record form, responding to the company's development status: the fourth generation refrigerant project successfully entered the trial production stage at the end of June 2026. Currently, all trial production work is proceeding according to plan, and downstream customer docking work is being carried out simultaneously. The company will seize the opportunity in the industry and continue to promote the downstream verification and market-oriented introduction of products.
03Dongyangguang 15000 ton PVDF expansion project environmental impact assessment approved
On September 29th, the Ecology and Environment Bureau of Shaoguan City issued a public announcement, intending to make an approval decision on the environmental impact assessment report of the "Ruyuan Dongyangguang Fluororesin Co., Ltd. Annual Production of 15000 Tons of PVDF Project". The total investment of this project is 200 million yuan, and the capacity of R142b will be increased by 17000 tons per year through renovation and expansion. After implementation, the R142b capacity of the entire plant will be increased from 63000 tons per year to 80000 tons per year; Increase the PVDF production capacity by 15000t/a, and after implementation, the PVDF production capacity of the entire plant will be increased from 35000t/a to 50000t/a. The project construction period is about 12 months, and the expected production date is October 2027.
04Hubei Yihua 2 × 30000 tons/year anhydrous hydrogen fluoride phase I project put into operation
According to the announcement from Yihua, Hubei on October 9th, the first phase of the wet process phosphoric acid supporting 2 × 30000 tons/year anhydrous hydrogen fluoride project has completed the construction of a 30000 ton/year anhydrous hydrogen fluoride plant. After review by relevant regulatory authorities, it has been safely and smoothly put into operation. The start and implementation time of the second phase project is uncertain, and the company will carefully study and determine it based on industry development and market conditions.