


IOL Fluorochemical Weekly Report: Refrigerant Foreign Trade Market Enters Final Stages, Prices Remain Stable
ChinaIOL
Refrigerant: Factory Centralized Foreign Trade Shipment Market Temporarily Stable Operation
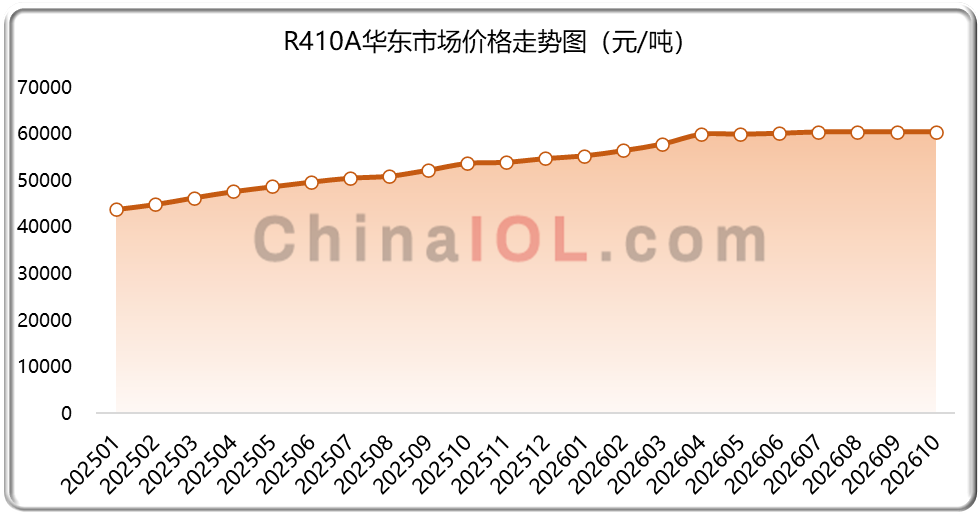
This week, the refrigerant foreign trade market entered its final phase, with prices remaining stable. Weekly market characteristics: Supply side: Factories continued to reduce production to maintain prices, with the operating rate of mainstream refrigerant products in the industry at around 50-60%. As November approaches, factories prioritized long-term orders and foreign trade orders, while domestic trade transactions remained relatively sluggish. Cost side: Fluorite powder faced tight supply but stable prices, while hydrofluoric acid, supported by both high costs and tight supply, saw a monthly price increase of approximately 800 yuan/ton. Other basic raw material products maintained moderate production and sales, with prices mostly rising and falling minimally, adjusting by around 5%. Demand side: The domestic market's after-sales procurement entered a slack season, with downstream demand primarily driven by necessary spot orders and weak follow-up purchasing intentions, resulting in overall low transaction activity. The foreign trade market, affected by extended shipping schedules and permit processing cycles, entered the final phase of the year's concentrated foreign trade shipments. Comprehensive projections indicate that the current annual quota is also nearing its end. Under the slack season conditions, reduced production to stabilize prices on the supply side, combined with persistently weak demand, suggests a high likelihood of maintaining a high-level consolidation trend in the market.
ChinaIOL
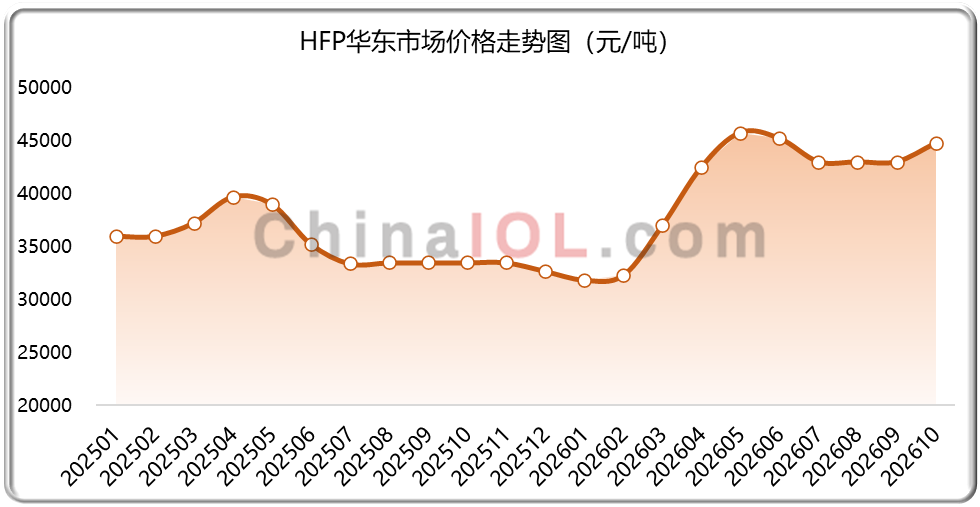
Fluorine-containing polymers: Off-season market sees more declines than gains, with prices mainly consolidating at low levels
This week, the fluoropolymer market continued to be supported by cost factors. Although mainstream products experienced rapid capacity growth, significant quality differences and varying operational rates across factories led to a fragmented and chaotic market trend. Prices of previously popular products such as fluororubber, PVDF, and PTFE remained close to the cost line, with limited room for further declines. On the cost side, prices of foundational raw materials like calcium carbide and hydrofluoric acid tightened due to supply constraints, resulting in substantial monthly price hikes. Methanol and ethylene prices fluctuated widely amid geopolitical tensions and import reductions, providing strong cost support for TFE series products. Intermediate products such as R22, R152a, and R142b faced pressure from both upstream and downstream sectors, leading to price volatility and cautious stabilization amid uncertainty. On the supply side, leading fluoropolymer manufacturers operated at high capacity levels, adjusting production schedules based on inventory and order status. On the demand side, the off-season market environment saw weak volume and price performance, with end-users adopting demand-driven procurement strategies. Notably, structural growth was concentrated in high-end segments: advanced semiconductor processes, AI computing infrastructure, and the new energy sector continued to drive demand for high-value-added products. Short-term production and sales of electronic-grade hydrofluoric acid, high-purity specialty fluorinated gases, semiconductor-grade PFA and PTFE, and AI data center liquid cooling fluorinated fluids remained relatively low. The price gap between high-end electronic-grade PTFE and general-grade PTFE stood at approximately 3x. The surge in demand for popular applications will create new growth opportunities for the industry. In the short term, fluoropolymer supply-demand dynamics remain weak, with sluggish demand being the primary factor, and prices are expected to consolidate in a low range.
Weekly news
01Shandong Aofan's fourth generation green refrigerant mixing and packaging project acceptance announcement
On October 26th, the Gaoqing Branch of Zibo Ecological Environment Bureau released a public notice on the acceptance of environmental impact assessment documents for the fourth generation green refrigerant mixing, packaging, and GMP product filling project of Shandong Aofan New Materials Co., Ltd. After the completion of the first phase of the project, an annual filling scale of 10000 tons of R1233zd/e, 5000 tons of R1234ze/e (including some R1234ze/e (GMP), belonging to pharmaceutical grade products), 1000 tons of R1234ze/z, 10000 tons of R1234yf, 5000 tons of R245fa, 1000 tons of R236ea, 2000 tons of R1233zd/z, and 2000 tons of R434a will be formed.
02Jinshi Resources: Significant decrease in revenue in the first three quarters of 2026
According to the third quarter report of Jinshi Resources in 2026, the operating revenue for the third quarter of 2026 was 238 million yuan, a year-on-year decrease of 76.98%; The net profit attributable to the parent company was a loss of 111 million yuan, with a deduction of non net profit loss of 111 million yuan. The operating revenue for the first three quarters of 2026 was 2.132 billion yuan, a year-on-year decrease of 22.69%; The net profit attributable to the parent company was a loss of 21.4301 million yuan, with a deduction of non net profit loss of 12.9811 million yuan. The company stated that its own mines in Zhejiang Province have temporarily suspended operations, and Jin'ebo Fluorine Chemical has temporarily stopped production due to safety rectification, resulting in a significant decrease in operating income during the reporting period.
03Sanming Haisifu Hexafluoroisopropanol and other product technology renovation projects announced
On October 26th, the Ecology and Environment Bureau of Sanming City issued a public notice on the acceptance of environmental impact assessment documents for the technical renovation project of fluorine chemicals such as hexafluoroisopropanol of Sanming Haisifu Chemical Co., Ltd. The project has an investment of 20 million yuan and is located in the existing factory area of the third factory in the industrial concentration zone of Mingxi County, Sanming City. It is planned to increase production capacity by 75693.87t/a; Reduce the production capacity of some existing products and plan to start trial production in December 2027.
04Change of Phase I Project of 50000 tons/year PVDF and Supporting Industry Chain Project of Lianchuang Shares
On the evening of October 23rd, Lianchuang Shares disclosed an important project change announcement, adjusting the first phase of the 50000 tons/year PVDF and supporting industrial chain project approved in 2022 to a "25000 tons/year PVDF and supporting industrial chain product project". The original plan for this project was to produce 25000 tons/year of PVDF and 45000 tons/year of R142b, with a total investment of approximately 1.6 billion yuan. After the change, the construction content is 25000 tons/year PVDF, with supporting 25000 tons/year VDF, 43750 tons/year R142b, and 30625 tons/year R152a. The total investment has been reduced to 937.5 million yuan, and the construction period is 24 months.